Common Reasons MSME Loan Applications Get Rejected (and How to Avoid Them)
Growing businesses such as MSMEs in India have contributed over 31% of the GDP in 2025-2026. With the numbers reaching almost one-third of the total, MSMEs are contributing substantially to India’s economic growth. But the growth is not linear; there are often operational hurdles or demand spikes that an MSME may not be equipped to face the sudden issues. There may be solutions available, but the business owners are often left asking:
Should I get a business loan for my MSME?
Digital borrowing has made the answer a simple yes. The borrowing process has changed to be much simpler and more convenient, with options specifically catering to growing MSMEs. Before starting an application, borrowers should check the lender’s requirements and understand common MSME loan rejection reasons to improve their chances of approval. This guide explores the common reasons MSME loans get rejected and what borrowers can do to avoid them.
Table of Contents
MSME Loan Rejection Reasons Explained
Understanding the common reasons why MSME loan applications get rejected can help new business owners prepare the right way for approval. Below are a few reasons why business loan gets rejected:
- Inaccurate or Outdated Documents – Submitting inaccurate or outdated business documents can create delays in approval or even cause rejections.
- Not Meeting Eligibility – If applicants submit without checking eligibility, it can lead to rejections, and borrowers may need to start the application process all over again.
- Credit Issues – If the business’s credit reports have any discrepancies or if they do not meet the criteria, it can also lead to rejections.
- High Existing Liabilities – If the business has several existing financial commitments, it can also lead to extended checks, delays and even rejections.
- Unclear Purpose of Loan – If the business does not have a clearly specified loan purpose in the application, it can cause delays or rejections.
Apply for a Business Loan up to ₹10,00,000 with Simple Eligibility Criteria Now!
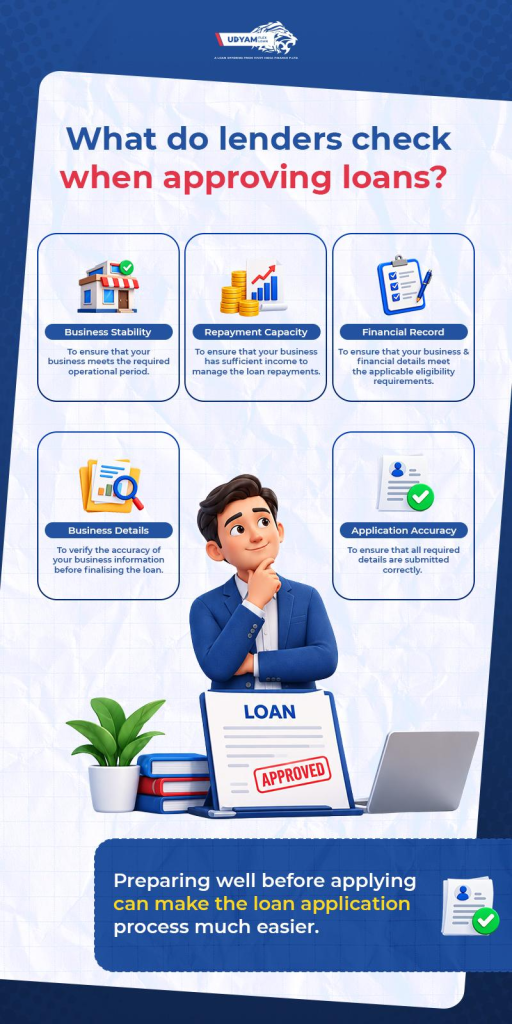
How Can MSMEs Prepare for an Application Process?
- Review the eligibility criteria
- Organise all the required documents
- Check the documents to ensure accuracy
- Check the required amount information
- Review the existing commitments
- Ensure that the details are consistent before submission
Continue Reading to Know More!
How to Avoid Business Loan Rejection
Preparing to avoid business loan rejection starts before submitting the application. Given below are a few checks and steps to take before applying to reduce the chances of rejection:
- Check and Submit Accurate Documents – Applicants should review and verify their documents to avoid delays caused by incorrect or outdated information.
- Check Credit History Before Applying – Check your credit reports to ensure there are no discrepancies and confirm that you meet the applicable credit requirements.
- Check Your Eligibility Before Submitting – New business owners need to confirm their eligibility before submitting the application, as it can lower their chances of rejection.
- Present a Realistic Business Plan – Your business plan should clearly communicate the intent of the business; it can lead to delays and application rejections.
- Ensure Regulatory Compliance – Ensure all the required registrations and documents are prepared before submitting; this can also help lower the chances of rejection.
How Udyam Flex Loan Helps Applicants with Simple Eligibility
One of the key details new business owners need to understand before applying for a business loan is the lender’s eligibility criteria. Clear eligibility criteria make it easier for applicants to understand the requirements and submit the necessary information, potentially reducing application issues. A digital lending app such as Udyam Flex Loan offers a business loan up to ₹10,00,000 with simple criteria and the following benefits:
- Minimal Documents: The documents required for a business loan from Udyam Flex Loan include ID proof, business proof and income proof for approval.
- Simple Eligibility Criteria: The eligibility criteria for Udyam Flex Loan include at least 6 months of operational history, Udyam registration, and a minimum income of ₹30,000.
- No Collateral Requirements: Udyam Flex Loan does not require collateral to approve business loans.
- Reports to Credit Bureaus: Udyam Flex Loan reports every monthly repayment to credit bureaus, which can help the business build or maintain its credit history when repayments are made on time.
- No Prepayment Penalties: Udyam Flex Loan does not charge an early repayment penalty on its business loans, allowing business owners to repay the loans earlier than the agreed-upon term with ease.
Conclusion
Loan rejection as a new business owner can feel like an obstacle, but a few checks before applying can improve the chances of approval. Borrowers need to check the general details, such as the accuracy of the documents and eligibility, before applying to lower the chances of rejection.
Choosing a lending app such as Udyam Flex Loan that offers a business loan up to ₹10,00,000 with simple eligibility criteria and minimal documents can lower the chances of rejection. When applying via Udyam Flex Loan, borrowers can also avoid prepayment penalties and asset pledging requirements to access a business loan. Apply now!
Simple Eligibility Criteria for a Business Loan up to ₹10,00,000 with Udyam Flex Loan. Apply Now!
FAQs
1. Can an MSME loan application be rejected even with Udyam Registration?
Udyam Registration is one of the requirements and does not guarantee approval for a business loan on its own. Borrowers also need to submit details such as documents, employment details, income, and other applicable requirements.
2. Do I need to submit collateral for an MSME loan?
Digital lenders do not require collateral to approve a business loan. Udyam Flex Loan offers a business loan up to ₹10,00,000 without asset pledging.
3. Can existing business loans affect a new MSME loan application?
If the applicant has existing financial commitments, they may be considered when assessing the business’s repayment capacity and eligibility for another loan.
4. Can I apply for an MSME loan again after rejection?
Borrowers should check the reason for rejection before applying again. Rejections usually happen due to documentation, eligibility, or credit-related issues, which should be checked before submitting another application.
5. How can I reduce the chances of my MSME loan application being rejected?
Borrowers need to check the lender’s eligibility criteria, keep the business’s financial documents updated and submit accurate information before submitting the application.